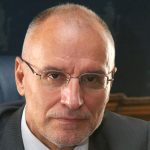
In a statement posted on the Bulgarian National Bank (BNB) website on September 25, central bank governor Dimitar Radev sharply criticised a proposal by Prime Minister Roumen Radev’s government for a windfall tax on various entities including banks.
Dimitar Radev warned of the potential impact on taxpayers: “Raising taxes has a cost. When the tax is on financial intermediation, some of that cost can be passed on to the taxpayer”.
This is his statement:
“Proposals for changes in tax legislation are part of the budget process. Decisions are within the competence of the government and the National Assembly. The BNB does not take sides in the political debate on budget priorities. It presents a professional assessment of the possible consequences of the proposed measure for the financial system and the economy.
These consequences affect financial conditions, lending, the sustainability of the banking system, and the interaction between fiscal policy and economic growth. From this perspective, the proposal for an additional tax on bank profits deserves a broader analysis.
Essentially, it is about increasing the taxation of banking activities. Defining it as a tax on “excess profits” does not change this fact. The question is whether the expected fiscal effect compensates for the consequences for financial intermediation and the economy. The answer requires more than an accounting.
The proposed mechanism has a clear budgetary logic: a historical profit base is determined, a legally established threshold is added, and the excess is taxed additionally. The expected revenue is relatively easy to calculate.
The macroeconomic account is different.
A bank’s profit is a tax base, but also a major internal source of capital formation. Capital determines its ability to take risk, provide credit and absorb losses in adverse economic developments. This is precisely why the BNB requires the accumulation of capital buffers in the good phase of the economic cycle: they must be available in the bad.
In 2020, this logic was put to the test. The BNB took measures to strengthen capital and liquidity, and banks implemented a private moratorium on loan payments. As of September, the deferral covered loans for more than nine billion leva. The buffers allowed banks to absorb the temporary pressure while businesses and households were given time to overcome the shock.
Therefore, current bank profits are not just income that can be distributed. Some of them support credit and the resilience of the system in the event of a future shock. This makes the definition of “excess profits” more complicated than the comparison between two accounting measures suggests.
The reference period 2020-2025 includes a pandemic, unusually low interest rates, an inflation and energy shock, and the subsequent sharp change in the interest rate environment. The beginning of 2020 was a crisis year with sharply reduced bank profits. Its inclusion in the historical average may present part of the subsequent recovery as “excess profits”. During the same period, bank balance sheets, loan portfolios, and capital grew, and significant structural changes occurred in individual institutions.
Under these conditions, the nominal profit in 2027 and the average nominal profit over the previous six years are not directly comparable. The higher absolute profit may contain economic rent, but it may also reflect a normal return on larger capital, a larger balance sheet, and additional risk taken. The distinction requires economic analysis, not normative assumption.
The more important question is what happens after the tax is introduced. Formally, it is paid by the banks, but its economic burden does not necessarily remain there. Banks can react with lower dividends – the most limited macroeconomic effect. However, the reaction can also pass through the cost of credit, credit standards, deposit conditions and asset structure. Then part of the burden is transferred to customers.
For the household, this may mean more expensive or more difficult to access credit; for the enterprise, a higher cost of capital. This cost determines which investment projects will be implemented. Banks are the channel through which financial resources reach the economy. Therefore, additional taxation of bank intermediation may to a certain extent make its use more expensive. The extent depends on competition, the capital position of individual banks and the credit cycle. It must be measured, not assumed.
International experience provides grounds for caution. In Hungary, the extraordinary taxation of banks, introduced as a temporary measure, was continued and modified along with other interventions in the credit market. It would not be correct to explain the high cost of credit there with a single tax: interest rates primarily reflect monetary conditions, inflation and the risk premium. But the policy mix is indicative – market corporate financing remains expensive, and the state also compensates for this through subsidized credit programs.
Bulgaria has no reason to follow such a model: first to increase the price of financial intermediation, and then to subsidize credit with public resources. The eurozone provides an opportunity for a lower risk premium, deeper financial integration and better conditions for the private sector. Unpredictable tax changes bring uncertainty for investors and, when they change the conditions for lending, can also affect the transmission of the common monetary policy to the economy. Economic policy should use the advantages of the eurozone.
There is a second channel. Bulgarian banks are among the main institutional investors in government securities. The same balance sheet that finances enterprises and households also participates in financing the state. With a higher cost of capital and more limited resources, banks may prefer low-risk government exposures to private credit. Then budget revenue may be accompanied by weaker financing of the private economy. If banks instead limit the increase in their exposures to government debt, the effect may be reflected in the price of government financing.
Both effects are important, especially when there is a significant need for new debt financing. Here, a time discrepancy stands out: the revenue from an extraordinary tax may be a one-off, while the higher interest on long-term government debt is paid over its entire maturity. Therefore, the assessment of the measure must include both the revenue for the budget and the costs of financing it.
The same applies to growth. If higher taxation leads to more expensive or selective credit, the effect will be felt in investment and consumption. Lower economic activity means a smaller base for VAT, corporate taxes, income taxes and social security revenues. Gross tax revenue and net fiscal result are different quantities.
After joining the eurozone, the main economic issue facing Bulgaria is no longer the exchange rate regime. It is how to accelerate investment, productivity and real convergence. The main driver must be the private sector. This implies a predictable tax environment, disciplined fiscal policy and a financial sector capable of directing resources towards productive private investment. Increasing the tax burden on this process must be carefully justified.
There is also a question of policy consistency. Macroprudential policy requires banks to build up capital buffers in the face of strong lending activity and high profitability. Fiscal policy proposes an additional seizure of part of the resource from which these buffers are formed. The two policies have different objectives, but their overall effect on capital needs to be assessed.
At the same time, the weakening of fiscal buffers limits the space for responding to a future shock. This risk should not be exacerbated by reducing bank buffers. If both types of reserves decrease simultaneously, the state will have fewer opportunities to mitigate the crisis, and banks will have less capacity to maintain credit. This would make the economy and the country more vulnerable to adverse developments.
The question is not whether the banking system can bear the additional tax. It is well capitalised, liquid, and profitable; there is no reason to dramatize the debate as a question of immediate financial stability. The question is whether the measure improves the overall economic outcome. That is the higher standard we should apply.
Before a final decision is made, the immediate budgetary assessment should be complemented by an assessment of the impact on capital, credit, interest rate conditions, investment, growth, other tax revenues and the cost of government financing. It should include a baseline and adverse scenario and take into account the interaction with macroprudential and monetary policy. Only then can the actual net effect be assessed.
This is not an argument in defence of bank profits, nor against the government’s right to propose changes in tax policy. This is an argument for the way such decisions should be made. Raising taxes has a cost. When the tax is on financial intermediation, some of that cost can be passed on to the taxpayer.
So the question is not just how much can be collected by the banks in 2027. The question is what the price will be for credit, investment and growth – and what the net result for public finances will be once it is accounted for. This is the difference between the accounting and macroeconomic policy.”
Bulgarian National Bank chief slams government’s proposal for windfall tax on banks 2026 THE NEWS FROM BULGARIA – NEWS AGENCY 2009-2025 2026-09-25 11:33:23
Latest news World news Country news Most important news latest news most important latest of the day Business News, Latest Business News, Business Updates, Global Business, Financial News, Business Headlines, Market News, Business Today. Stock Market News, Financial Markets, Investment News, Banking News, Corporate News, Company News, Economic News, Business Reports. Global Markets, Market Updates, Stock Market Updates, Business Analysis, Finance News, Banking Updates, Investment Updates, Economic Updates. Entrepreneurship News, Technology Business, International Business, Business Trends, Market Analysis, Corporate News Today, Business Breaking News, Financial Markets Today. Business World, Global Economy News, Economic Trends, Latest Financial News.
BULGARIA NEWS – NEWS AGENCY 2009–2026 2026-09-25 11:33:23